Insurance for manufacturing and warehouses
Plan coverage around keeping goods moving
Ting Insurance Services LLC is an independent agency that helps California manufacturers and warehouse operators explore available insurance options for their operations.
Tell us what you make or store, and which equipment your operation depends on.
Why work with us
- Your operation comes first. We take the time to learn about your goods, equipment and workflow before we quote.
- Plain answers. We explain what your current policy covers and what it leaves out, then discuss the coverage questions for the work you do.
- We review what you have now. As part of every quote, we review the current policy and coverage documents you provide. That includes before your renewal.
- Options from several insurance companies. As an independent agency, we look at options for your operation.
What we look at before we quote
- What you make or store. What materials and finished goods do you handle? Tell us about dust-producing work, lithium-ion batteries and plastics.
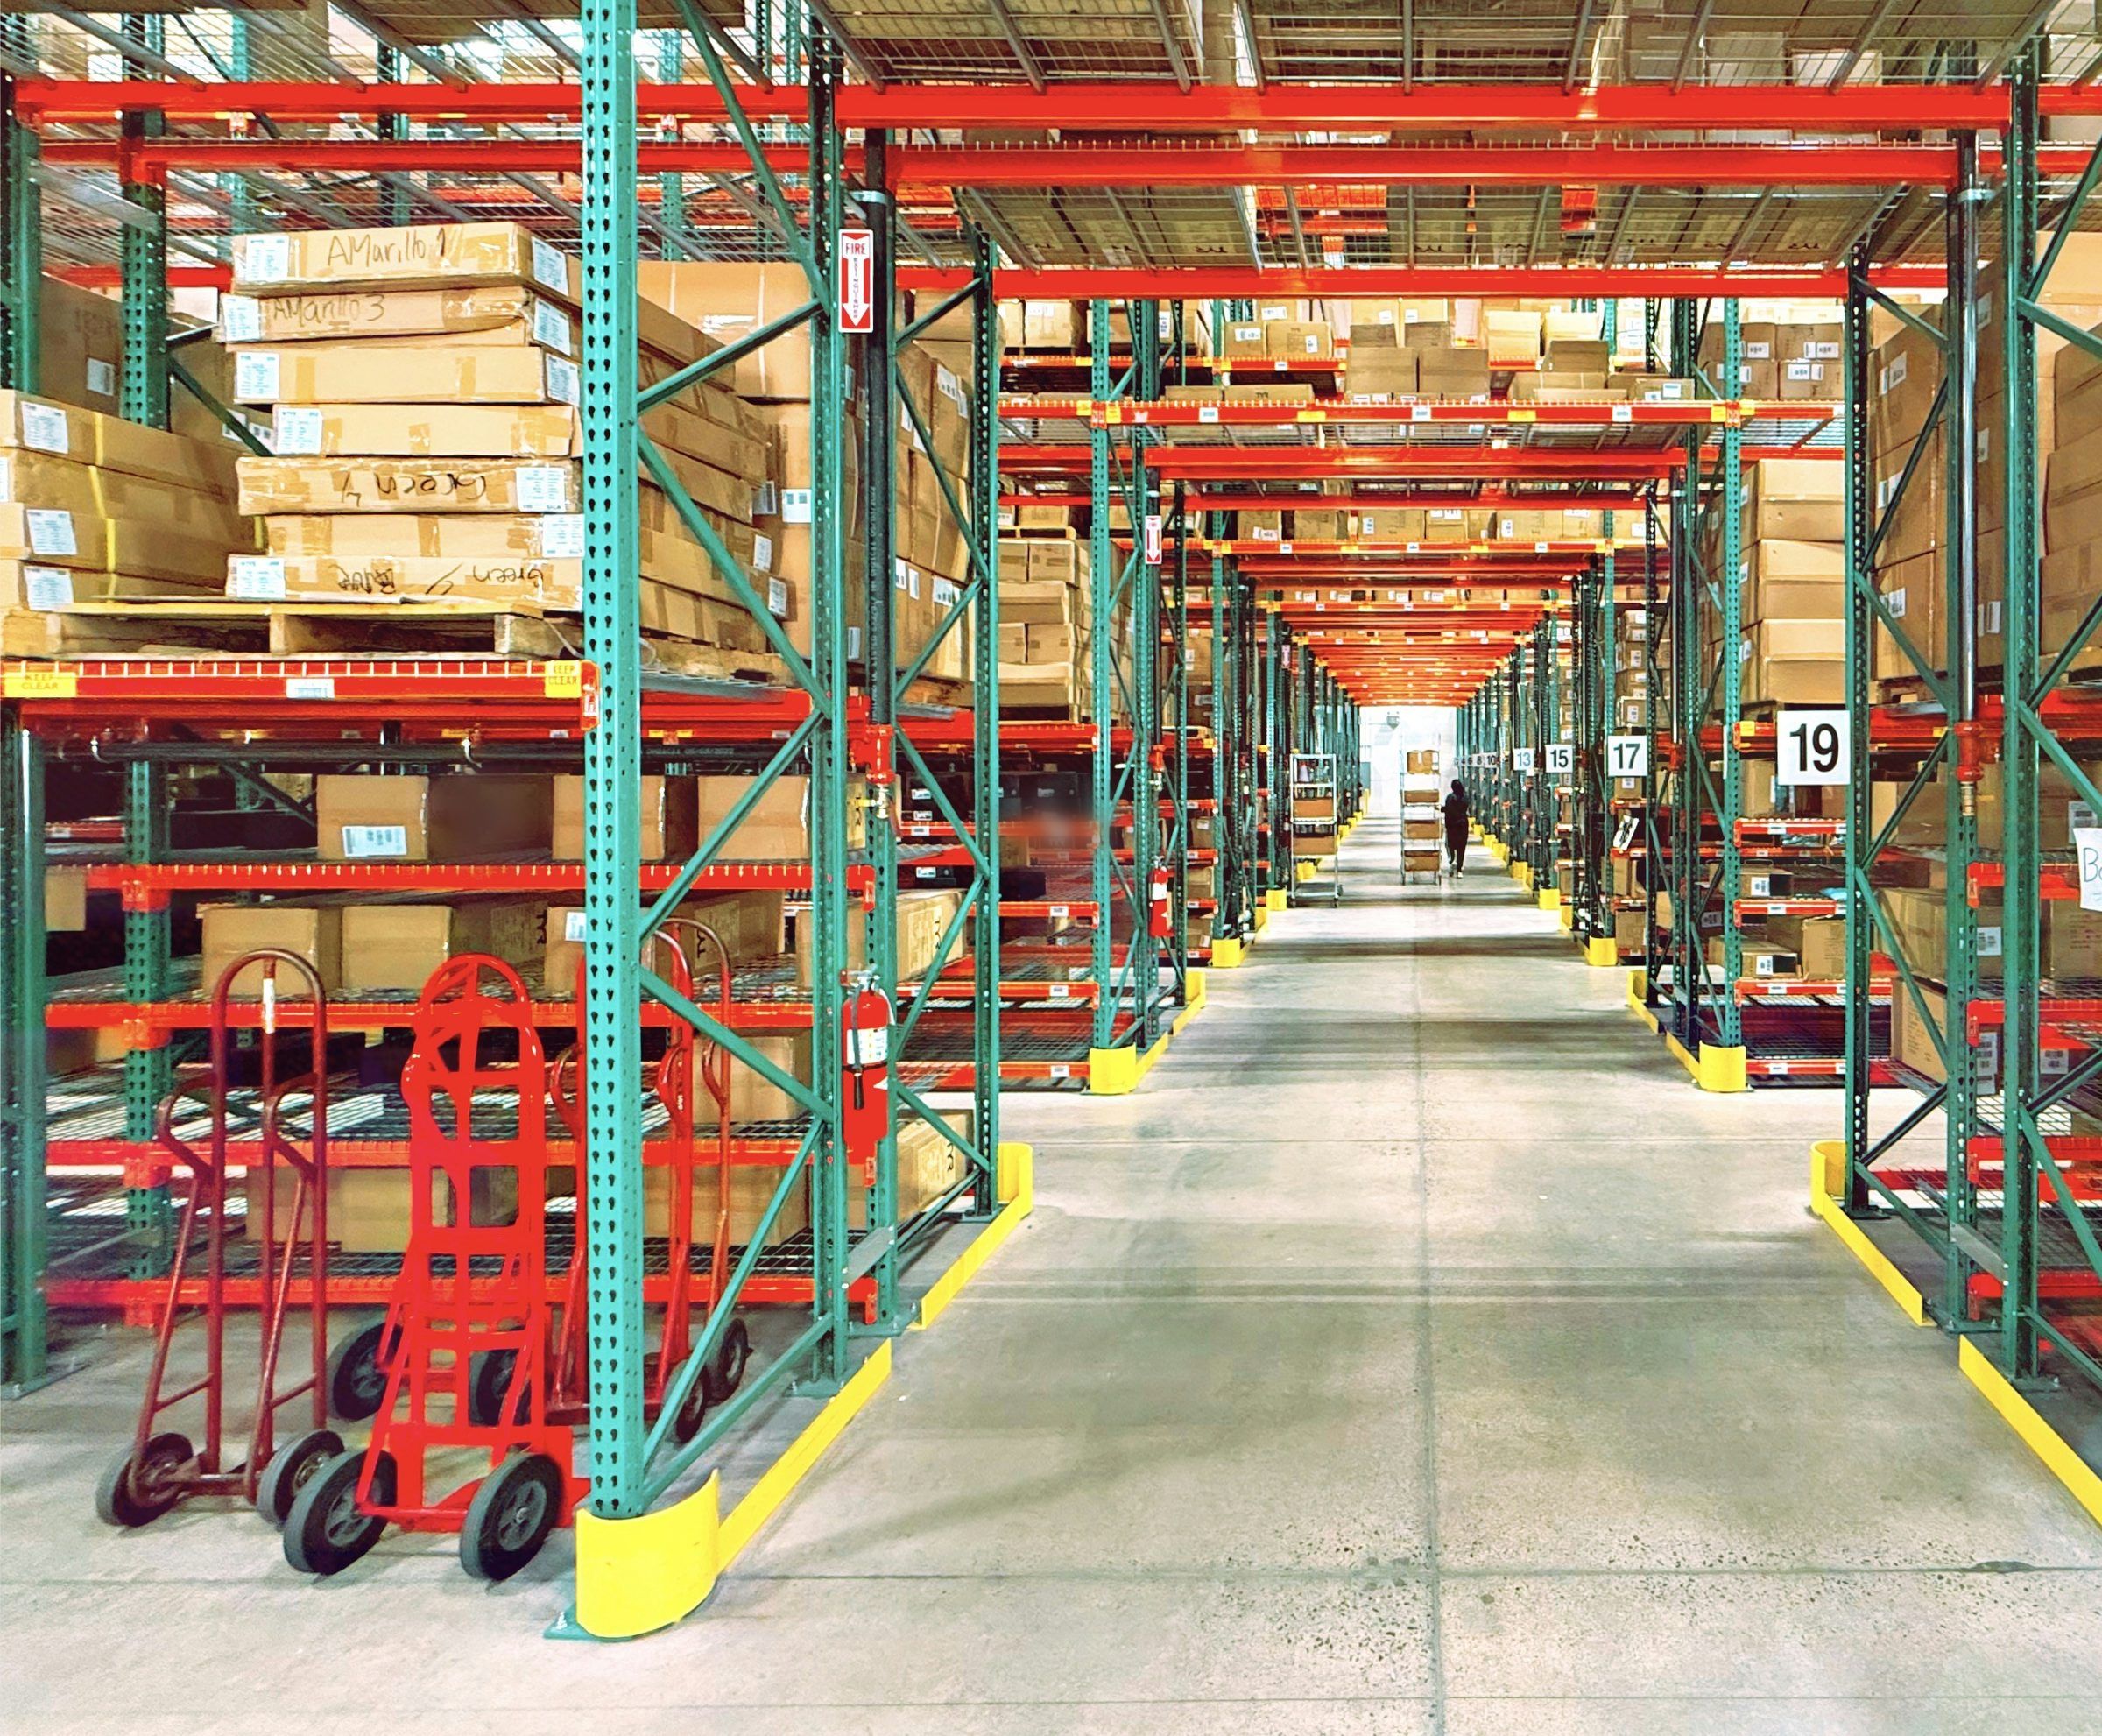
- Storage and sprinklers. How high is stock stored, and has a fire-protection professional reviewed changes in the goods or layout?
- People and handling work. Who lifts, picks, packs or operates machinery? What lifting aids and separate walking routes do you use?
- Pickups and deliveries. How do you confirm the authorized driver and vehicle, and handle last-minute changes before releasing a load?
- Electrical equipment and hot work. Which machines are critical, what service records do you keep and how is welding or cutting handled?
What happens next
Tell us about your operation. Start with the quote form or book a call.
Have a current policy? Upload it in the quote form or email it to hello@tinginsurance.com. We review your current coverage.
We review your request and contact you.
We go through your options with you. We explain the differences and the questions to resolve before you choose.
Coverages manufacturers and warehouse operators usually look at
The right coverage depends on the goods, equipment, people and policy terms. These links begin the review; they do not include every risk below.
- Business owners policy (BOP): Review the building, equipment and stock, plus the causes of damage included.
- Commercial package: Discuss selected property and liability parts, and ask about equipment breakdown and business income.
- General liability, including products: Describe what you make, import or distribute and ask about products coverage and exclusions. Keep supplier and product records together for this discussion.
- Workers' comp: Describe production, picking, packing, forklift and delivery duties.
- Business auto: Review company vehicles, rentals and employees driving their own cars for work.
- Goods in transit: Ask about coverage for goods moving by truck within the US. The formal name is inland marine, a type of property coverage that includes goods in transit.
Shipping goods by sea? See Ocean cargo.
Common causes of loss, and what helps
Common problems to check in a plant or warehouse. The evidence includes national warehouse fire data, California manufacturing injury surveys and cargo tracking. A cause on this list is not always covered; your policy decides.
Electrical and equipment fires (show details)
Fire spreading through stored goods (show details)
Cargo theft and fake pickups (show details)
Lifting and machinery injuries (show details)
What to check:
- Review lifting aids for repetitive case handling.
- Keep walking routes separate from forklift routes where possible.
- Check racks for bent uprights and missing or damaged anchorage; have concerns assessed before continued use.
Equipment breakdown (show details)
Let's talk about your operation
Tell Ting Insurance Services LLC what your business handles and the coverage questions you want answered.
Sources (1)
- Understanding inland marine insurance - Insurance Information Institute. Accessed Nov 6, 2026. It describes products, materials and equipment moving over land, including by truck or train.