Office and retail building insurance
Your building and rental income, considered together
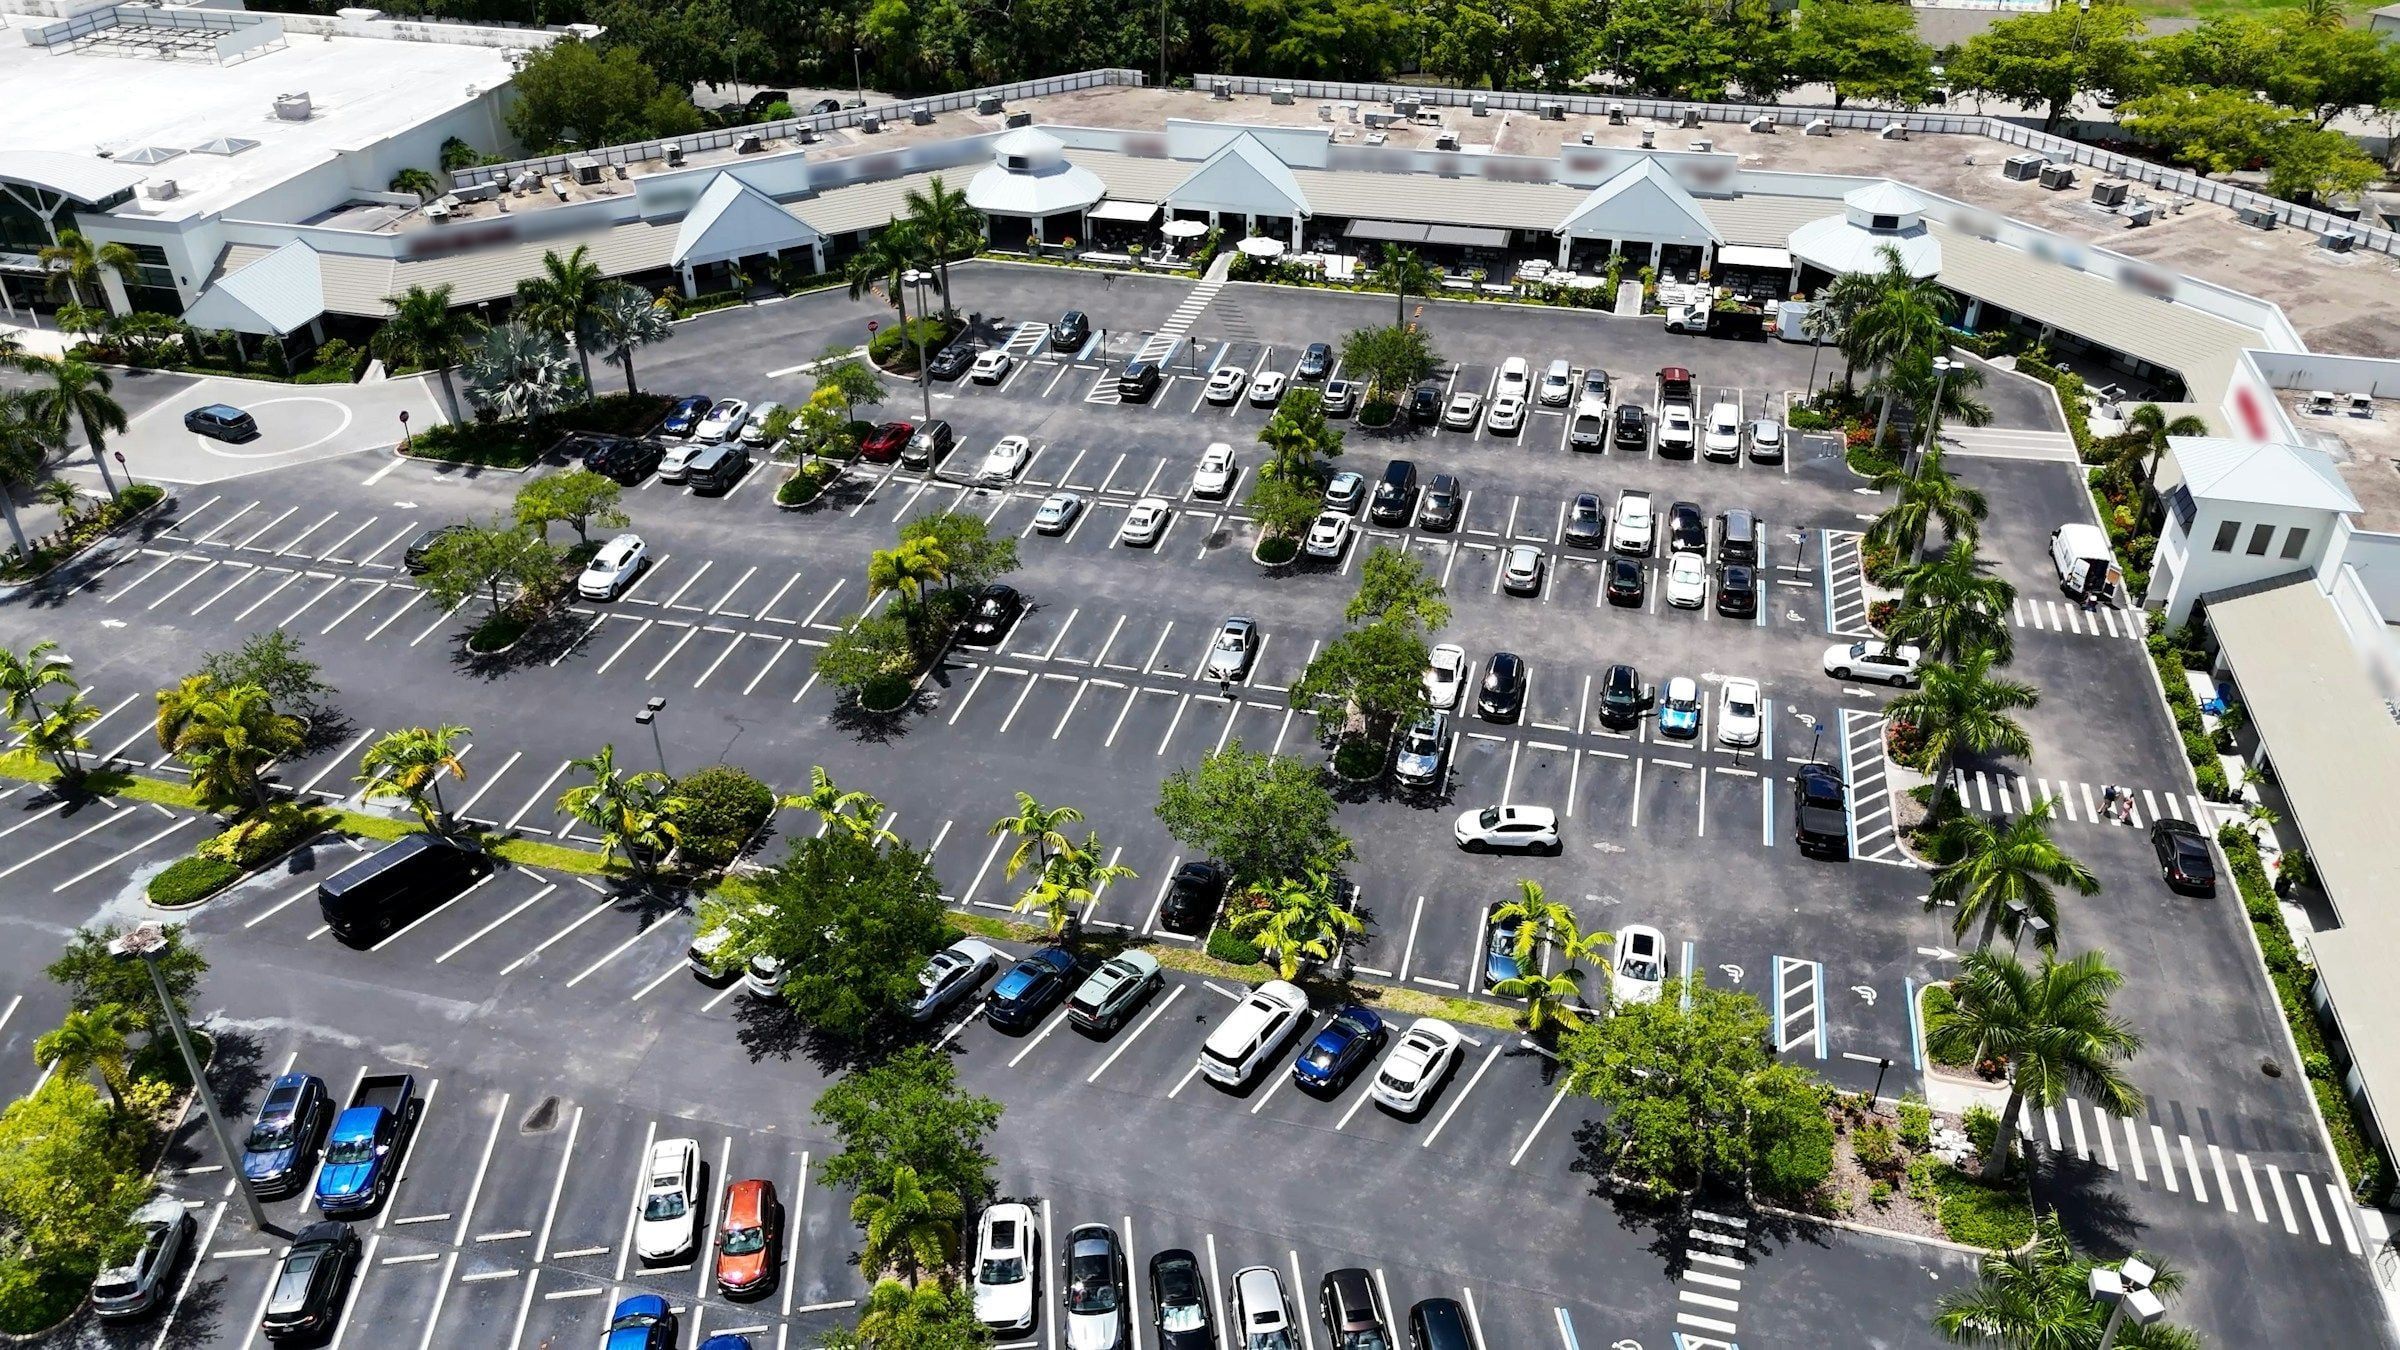
Your office or retail building is part of your income and your plans. Bring your current office and retail building insurance policy so we can discuss the property, tenants and rental-income coverage questions together.
What it usually covers
- The insured building. Protection for the structure, completed additions and permanent fixtures.
- Owner-owned business property. Coverage for equipment, furniture and other business contents you own rather than a tenant's stock.
- Premises liability. Help with covered claims involving accidental injury or property damage arising from the property or your operations.
- Lost rental income. Coverage for insured rental-income loss while covered damage leaves space unfit to occupy.
- Optional equipment breakdown. Ask about coverage for mechanical or electrical breakdown involving building systems such as heating and air conditioning.
Who it is for
For owners reviewing an office building or a small group of retail spaces. Start by telling us whether you lease the whole property, occupy part of it yourself or have empty suites. Bring the leases so the review starts with your actual responsibilities.
A Commercial package can combine property and liability coverage parts. A Business owners policy may be worth discussing for a qualifying small operation, but business type and size matter.
We look at your property and your liability together, in one review. As part of every quote, we review the current policy and coverage documents you provide.
Rent a suite for your own business rather than own the building? Start with the Business owners policy page and bring your lease.
What to have ready
Start with these details for a conversation about the building:
- Address, ownership entity and current policies.
- Building size, construction, age and major system updates.
- A tenant list describing the work done in each suite.
- Leases, annual rental income and details of vacant space.
- A rebuilding estimate and a list of owner-owned equipment.
- Available claims history and any renewal or nonrenewal notice.
Common questions
Does the building policy insure a tenant's inventory? (show answer)
Is equipment breakdown the same as building coverage? (show answer)
Is my building's market value the rebuilding cost? (show answer)
What if I also run my business in the building? (show answer)
Start with your building and your leases
Share your current coverage and tenant list so we can begin with the property you actually own.
We review your request and contact you.
Sources (2)
- Commercial Insurance Guide - California Department of Insurance. Accessed Nov 1, 2026.
- Small Business Property Insurance - Triple-I. Accessed Nov 1, 2026. Used for owner/tenant property responsibilities, not form-specific limits.